The ACA Marketplace "Subsidy Cliff"

August 26, 2026

What It Means for Your 2026 Coverage


If you buy your own health insurance, you may have noticed your 2026 premium jumped. A lot of people did. Here's what happened, who it hit hardest, and what you can do about it.


The Short Version


For the past few years, extra financial help lowered monthly premiums for people who buy coverage through the Health Insurance Marketplace. That help was called the enhanced premium tax credit. It started in 2021 and ran through the end of 2025. It expired on January 1, 2026.

When it expired, the older rules came back. One of those rules is the "subsidy cliff."


What Is the "Subsidy Cliff"?


The subsidy cliff is an income cutoff. Under the current rules, if your household income goes above 400% of the federal poverty level, you no longer qualify for a premium tax credit. Not a smaller credit. No credit at all.


The exact cutoff depends on your household size. For 2026, it is approximately $62,600 for a single person and $84,600 for a two-person household. Earn a dollar over that line, and you could be responsible for the full health insurance premium on your own.


That's why people call it a "cliff". Stay just under the line, and you may get help. Go just over it, and the help can disappear.


Who It Hit Hardest


Older, middle-income people have generally felt it the most. There are two reasons for that. First, they tend to sit closer to that income line. Second, premiums rise with age.


Here's a real example from the Bipartisan Policy Center. A 60-year-old couple earning about $85,000 a year sits at roughly 402% of the poverty level. That puts them just over the cliff. Their estimated yearly premium for 2026 could reach about $22,600. That's close to a quarter of their income. Under the enhanced credits, their cost would have been capped near 8.5% of income.


The enrollment numbers tell the same story. People earning just above the cliff, between 400% and 500% of the poverty level, made up only 3% of 2025 sign-ups. But they accounted for 27% of the decrease in sign-ups from 2025 to 2026, according to KFF. Many looked at the new price and walked away.


What This Means for You


Marketplace credits are calculated from the income you report, so if you end up earning more than you estimated and cross the 400% line, you may have to pay some of those credits back at tax time. For 2026, that risk is bigger than it used to be. Recent law removed some of the caps that once limited how much certain enrollees had to repay.


This is why small income changes can matter so much near the cliff. A raise, a year-end bonus, or a stretch of extra freelance work could be enough to push you over the line and significantly change what you owe.


What You Can Do


Review your options during open enrollment. Don't assume last year's plan is still your best fit for this year.


Compare plan levels. Some people move to a plan with a higher deductible to bring down the monthly cost. That trade-off works for some budgets and not others, so look at the full picture of all your costs (monthly premiums, anticipated out-of-pocket medical costs, etc.).


Estimate your income carefully. KFF and HealthCare.gov both offer calculators that can help you see where you may land and what help you may qualify for.


Talk to a licensed agent. An agent can walk you through the choices based on your income, your household, and your area. This is one of those decisions where a real conversation with a knowledgeable agent helps.


One More Thing to Watch


Congress has been debating whether to bring the enhanced credits back. The House passed a three-year extension in early 2026, and lawmakers have floated several other versions with different income limits and rules. As of now, nothing has been finalized, and the rules could still change. For the latest, check HealthCare.gov or your state's Marketplace.


The subsidy cliff is real, and it can be steep. But you still have options, and an insurance agent can help you understand your costs and tradeoffs. The sooner you understand your numbers and options, the better the choices you can make.


Sources


KFF, the Bipartisan Policy Center, CNBC, and the Congressional Research Service. Premium figures are estimates and will vary by age, plan, household size, tobacco use, and location. This content is for general education and is not a guarantee of coverage, savings, eligibility, or any specific outcome.

Share

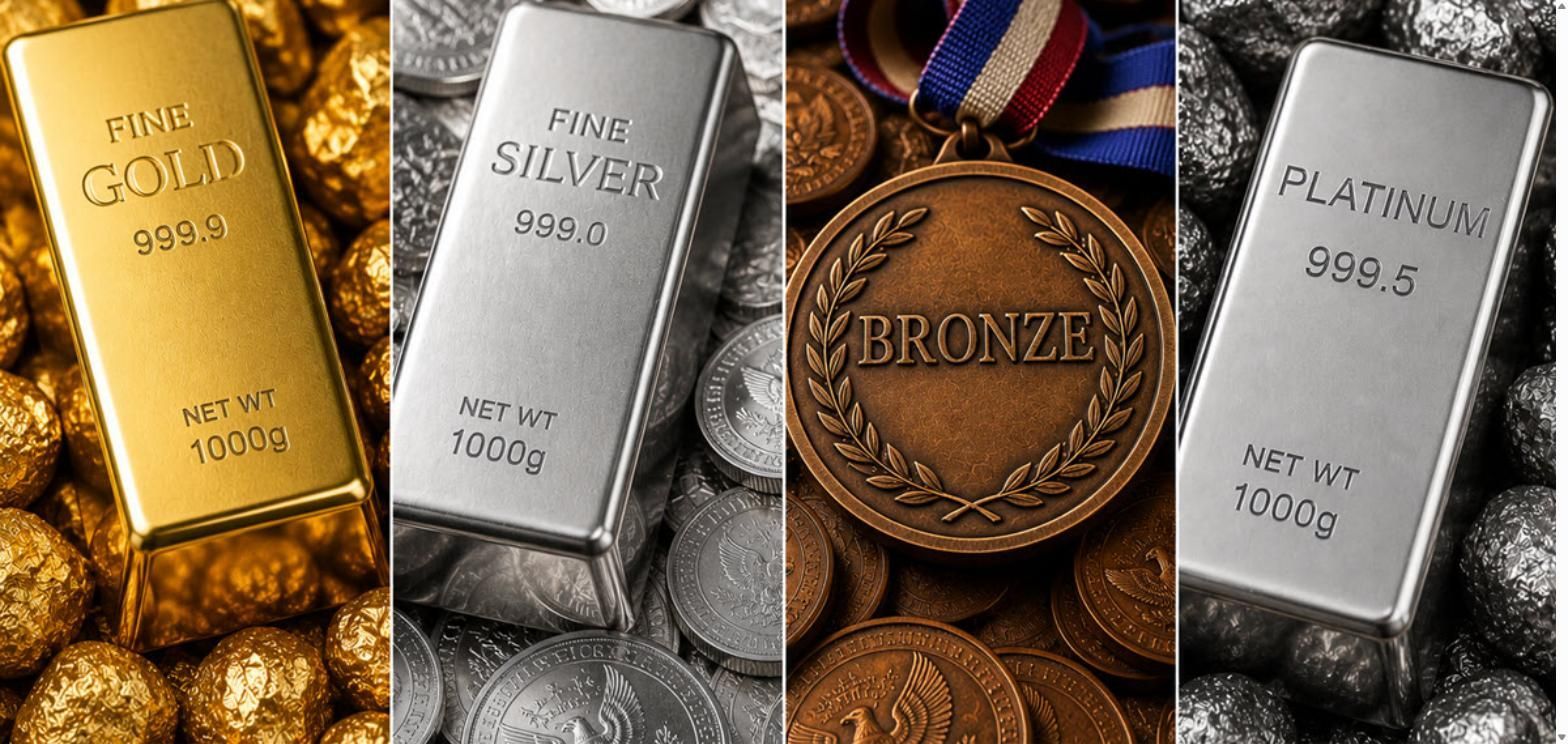
Gold, silver, and platinum bullion bars beside a bronze medal, representing Marketplace health plan metal tiers.
By Dyani Galligan August 19, 2026
A clear guide to Health Insurance Marketplace metal tiers. Learn how Bronze, Silver, Gold, and Platinum plans split costs and how to pick the right one.
A smiling older man rides a red four-wheel mobility scooter along a tree-lined park path on a sunny autumn day.
By Dyani Galligan August 12, 2026
Thinking about a wheelchair or mobility scooter? Learn what Medicare covers under Part B, what your doctor must document first, and how to avoid a denied claim.
Person holding a stack of mail and a letter in a living room with a coffee table
By Chris McGaw August 7, 2026
Every fall, Medicare Advantage and Part D plans mail an Annual Notice of Change. Learn what it means for your costs, coverage, and doctors next year.
A home health nurse in a face mask assists an older man seated in a chair, illustrating chronic condition care under a Medicare C-SNP.
By Dyani Galligan August 5, 2026
A Chronic Condition Special Needs Plan (C-SNP) is a Medicare Advantage plan built around conditions like diabetes or heart failure. See how it works.
Open notebook with wooden letter tiles spelling
By Alpine Advantage Health Insurance January 30, 2026
At Alpine Advantage Health Insurance , we’re committed to doing more than just helping people enroll in coverage — we focus on delivering a level of service that makes the process easier, clearer, and far less stressful. That’s why we’re always honored when our community takes the time to recognize the work we do. Voted Best Insurance Agency in Lancaster County We’re excited to share that Alpine Advantage Health Insurance was recently voted the top insurance agency and top insurance agent in Lancaster County, South Carolina , through a community poll hosted by thelancasternews.com .  Thank You for Your Support We’re truly grateful to everyone who took a moment to vote for us. Your support means a lot, and we don’t take it for granted. Whether you’ve worked with us for Medicare, individual health insurance, or just needed guidance on your options, we’re thankful you chose Alpine Advantage Health Insurance. Our goal is to continue earning your trust by being the resource you can rely on — not just during enrollment season, but year-round whenever questions come up. We’re Here When You Need Help If you need help comparing plans, understanding Medicare, or finding the right health insurance for your situation, we’d love to help. Contact Alpine Advantage Health Insurance today to get personalized support and clear answers.
A bunch of soda cans are stacked on top of each other
July 1, 2025
Understand the health risks of soft drinks & explore healthier alternatives. Make informed choices for your well-being today!
A woman is holding a map in front of her face while leaning on a car.
July 1, 2025
Get 7 healthy travel tips for safe adventures. Learn about Medicare coverage & supplemental insurance options. Prepare for your journey today!
The word scam is written on a piece of paper next to a pile of money.
July 1, 2025
Learn to spot the grandparent scam targeting seniors. Get tips to protect your loved ones from financial fraud today!